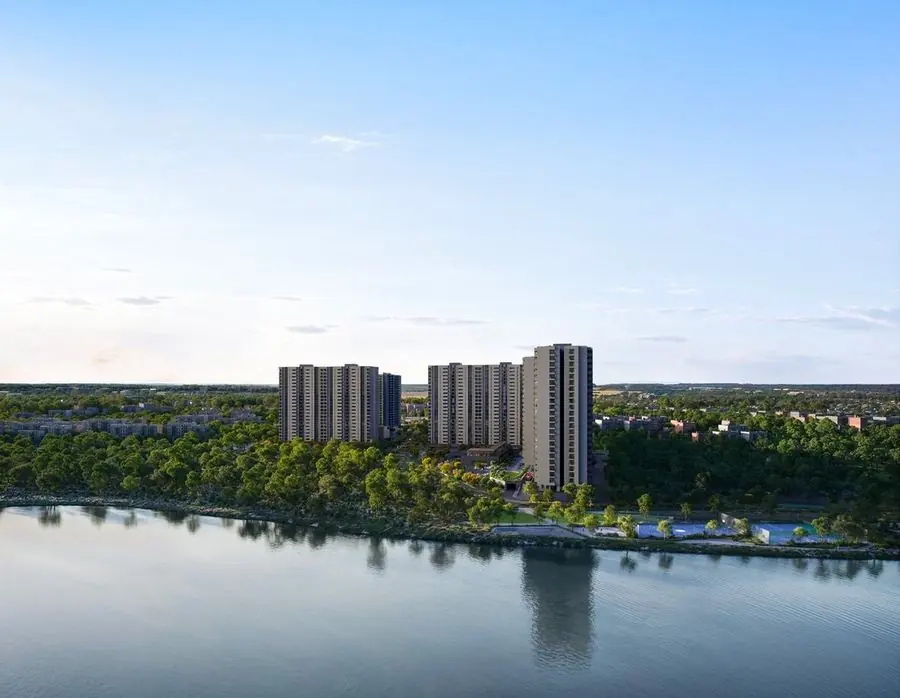
The Assetz Mizumi Reserve price starts at ₹2.57 Cr all in for a 1,901 sq.ft. 3 BHK, and the 2,476 sq.ft. 4 BHK comes to ₹3.39 Cr, both before stamp duty and registration. Those figures come from the developer's official sample cost sheets. The hoarding says ₹10,700 per sq.ft.; the cheque works out closer to ₹13,500. Both are true, and the gap between them is where most buyers get surprised. Here is every line.
Mizumi Reserve price at a glance
| Layout | Super built up | Carpet (RERA + balcony) | All in price |
|---|---|---|---|
| 3 BHK Type 1 | 1,901 sq.ft. | 1,431 sq.ft. | ₹2.57 Cr* |
| 3 BHK Type 2 | 2,165 sq.ft. | 1,648 sq.ft. | ₹2.96 Cr* |
| 4 BHK | 2,476 sq.ft. | 1,869 sq.ft. | ₹3.39 Cr* |
* From the developer's sample cost sheets, valid to 5 February 2026, before stamp duty and registration. The price of a specific unit depends on its floor and position.
The 3 BHK: 1,901 sq.ft. on the 10th floor
This is unit A-1096, a 3 BHK in Tower A-1. The rate per sq.ft. is built up first:
| Rate component | Per sq.ft. |
|---|---|
| Base rate | ₹10,700 |
| Floor rise | ₹270 |
| Premium location | ₹200 |
| Rate you actually pay | ₹11,170 |
Then the full sheet:
| Line | Amount |
|---|---|
| Base cost (1,901 × ₹11,170) | ₹2,12,34,170 |
| Car park (1) | ₹3,25,000 |
| Clubhouse | ₹3,25,000 |
| Infrastructure | ₹21,86,150 |
| Total before GST | ₹2,40,70,320 |
| GST | ₹12,03,516 |
| Legal, 1 year maintenance, sinking fund | ₹3,81,195 |
| All in | ₹2,56,55,031 |
If you have not read a builder's cost sheet before, our guide to every line on a Bangalore cost sheet explains what the infrastructure charge covers and why GST works out to 5%.
The 4 BHK: a sample 2,476 sq.ft. unit
This is a sample 4 BHK, unit A-4094 in Tower A-4, on a high floor. The rate is ₹10,655 base, plus ₹270 floor rise, plus ₹400 premium location, which gives ₹11,325 per sq.ft. On 2,476 sq.ft. the base cost is ₹2,80,40,700. The total before GST, including two car parks at ₹6,50,000, is ₹3,18,63,100. GST, legal charges, maintenance and the sinking fund add ₹20,68,236. All in, it comes to ₹3,39,31,336, or about ₹13,704 per sq.ft.
Note that the 4 BHK has a lower base rate than the 3 BHK but a higher real rate, because its location premium is double and it carries a second car park.
The larger 3 BHK: 2,165 sq.ft. Type 2
A third sample sheet, unit A-1095 on the 10th floor, prices the larger 3 BHK. The rate is ₹10,665 base, plus ₹270 floor rise, plus ₹350 premium location, which gives ₹11,285 per sq.ft. All in, it comes to ₹2,95,58,415, published as ₹2.96 Cr*, or about ₹13,653 per sq.ft. That is about ₹39 lakh more than Type 1 for 264 sq.ft. more super built up area.
What is not on the sheet
Stamp duty and registration are paid to the government, not the developer, so they never appear on a cost sheet. In Karnataka they add about 6.6% on a home of this size: 5% stamp duty, 10% cess and 2% surcharge on that duty, and 1% registration. On the 3 BHK that is roughly ₹16.9 lakh more, and on the 4 BHK roughly ₹22.4 lakh, depending on the final agreement value. It is payable on registration day, usually from your own funds rather than the loan. How stamp duty and registration are worked out in Karnataka.
How you pay it
The plan is construction linked. Approximate amounts below are worked on the 3 BHK's all in total; the developer's demand letters set the exact figure at each stage.
| Stage | Share | Roughly, on the 3 BHK |
|---|---|---|
| Booking (₹5 lakh on the day, balance within 10 days) | 10% | ₹25 lakh |
| Agreement to sale, within 30 days | 10% | ₹25 lakh |
| Construction linked, slab by slab | 65% | ₹1.67 Cr over the build |
| Flooring | 5% | ₹13 lakh |
| Painting | 5% | ₹13 lakh |
| Possession | 5% | ₹13 lakh |
So about 20% of the price is due in the first month, and the rest over the build to possession in 2030. On a home loan, pre EMI interest runs only on what has been paid out.
What would the EMI be?
For a home above ₹75 lakh, RBI rules cap the loan at 75% of the value, so plan on a 25% down payment. On the ₹2.57 Cr 3 BHK that leaves a loan of about ₹1.92 Cr. The monthly EMI changes a lot with the rate and the tenure:
| Loan | Rate and tenure | EMI, approx. |
|---|---|---|
| ₹1.92 Cr (3 BHK) | 8.5% over 20 years | ₹1.67 lakh |
| ₹1.92 Cr (3 BHK) | 9.0% over 20 years | ₹1.73 lakh |
| ₹1.92 Cr (3 BHK) | 8.5% over 25 years | ₹1.55 lakh |
| ₹2.54 Cr (4 BHK) | 8.5% over 20 years | ₹2.21 lakh |
These rates are assumptions, not quotes. Your bank sets the rate on your profile. Try your own numbers in the EMI calculator.
What to check before you pay a booking amount
- The date on the sheet. Both samples were valid to 5 February 2026. Launch prices move, so ask for this week's sheet.
- Your unit's floor rise and location premium. They differ unit by unit; the two samples already differ by ₹200 per sq.ft. on location alone.
- The infrastructure clause. If government rates change before you finish paying, the difference is usually passed to the buyer.
- The RERA completion date. The developer's schedule says 2030; the date registered on RERA is the one that binds.
Price is only half the decision. Our honest Mizumi Reserve review covers phasing, the commute and who the project suits.